
Australia Faces a Fifth Rate Rise in 2026: The Psychology of Waiting for the RBA
Reviewed by a Psychology Postgraduate (MA)
On Tuesday 3 November 2026 — Melbourne Cup Day — the Reserve Bank of Australia announces its latest interest rate decision, due at 2:30 p.m. Sydney time, and the Australia RBA rate hike psychology starts right there, in the wait before the announcement. All four major banks expect the cash rate to rise by 25 basis points, from 4.60% to 4.85%, which would be the fifth increase of 2026 and the highest cash rate since late 2008. The trigger is inflation: headline CPI reached 4.3% in the year to September, up from 4.0% in August, while underlying inflation, the trimmed mean the RBA watches most closely, sits around 3.6 to 3.7%, well above the bank’s 2 to 3% target band.
The short answer: Australia RBA rate hike psychology is about dread before a decision you cannot influence: mortgage holders do the math in advance, imagine the worst version of the announcement, and then live inside that imagined future for days before anything actually changes. The rate decision is a number. The anxiety is the story households tell about what the number means for their home, their job and their plans.
Financial anxiety is the worry and restlessness that comes from uncertain money pressures — rising repayments, shrinking budgets, and the feeling that the ground under a household is shifting. A rate decision concentrates all of that into a single afternoon.
Why does waiting for an RBA rate hike feel so personal?
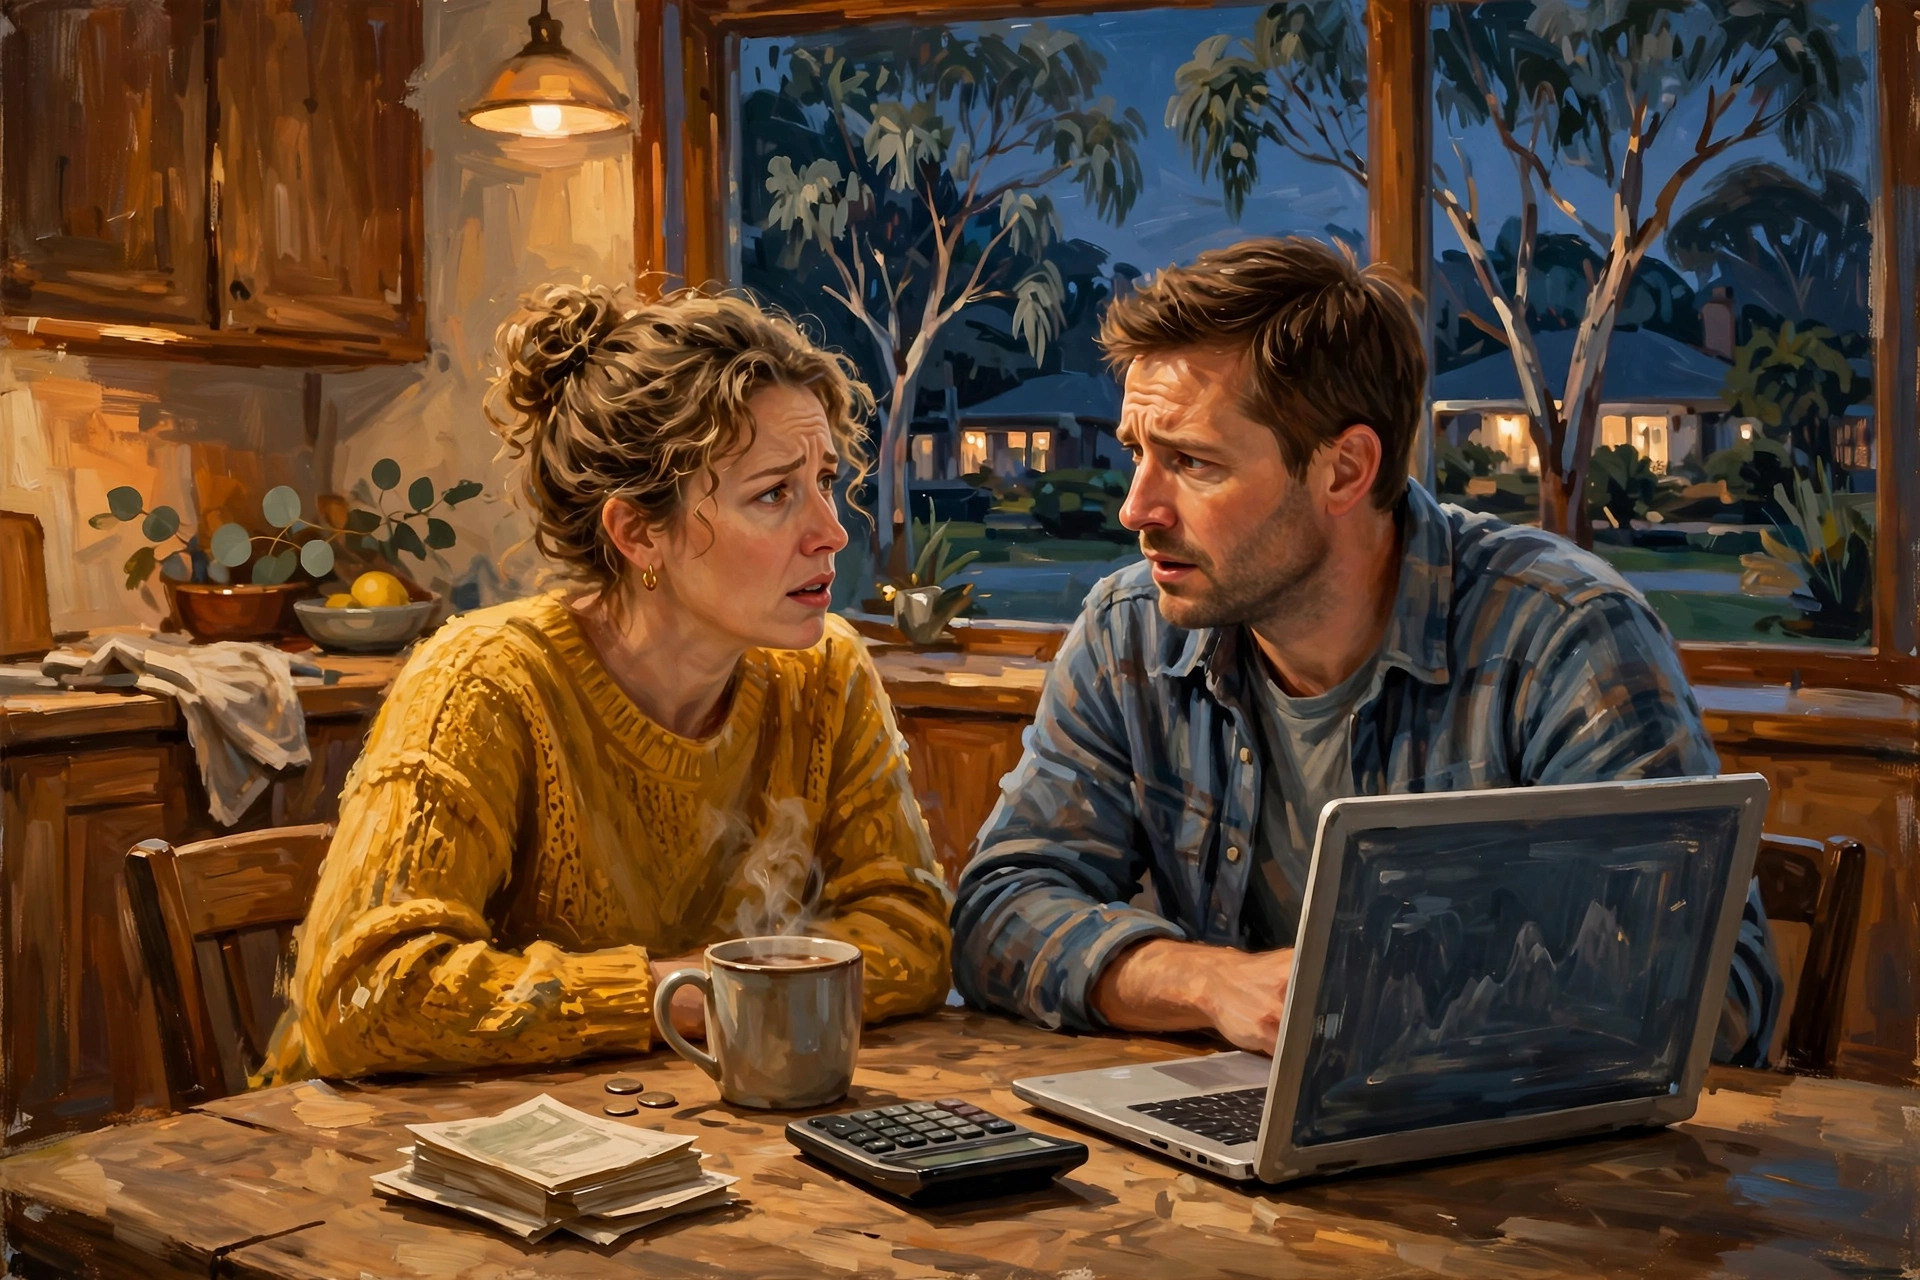
Because a cash rate is abstract, but a mortgage repayment is not. For a household that has already absorbed four rises this year, a fifth is not a statistic. It is a specific monthly figure, a redrawn budget, a holiday canceled or a renovation postponed. The brain converts percentages into pictures: the kitchen table, the bank app, the conversation with a partner about what gives.
That is also why the days before the announcement feel worse than the announcement itself. Commonwealth Bank economists now expect growth to slow to 1% by mid-2027, and they warn that households will carry much of the burden of a sharper slowdown. When the forecast is gloomier than the present, people start grieving a future that has not happened yet — a psychological pattern called anticipatory anxiety, where the mind rehearses a loss in advance and feels it in the present tense.
Consider a couple in western Sydney with a variable-rate mortgage. They have already reworked their budget four times this year. This week they are not waiting for a number. They are waiting to find out whether the fifth rework is needed, and whether the sixth is coming in February. The uncertainty is the tax, and it is charged daily.
Why do we overestimate the damage of bad money news?
Because of loss aversion, one of the most reliable findings in behavioral economics: losses feel roughly twice as powerful as equivalent gains. A $200 rise in a monthly repayment does not feel like the mirror image of a $200 pay rise. It feels bigger, heavier and more threatening, because it touches the home — the place the mind files under safety, not spending.
News coverage amplifies the effect. Headlines lead with the highest plausible figure, the longest plausible tightening cycle, and the gloomiest forecast available. JPMorgan now expects the RBA to keep a tightening bias while inflation stays high, and markets price roughly a 90% chance of a rise today. Those are careful, conditional statements. By the time they reach a household feed, they read as certainties: rates up, more to come, no relief until 2027.
Pause and ask yourself: What is the actual number I am afraid of — the repayment figure, the total, or the feeling that I am falling behind? Naming the figure usually shrinks the fear. Naming only the feeling lets it grow.
How does rate-rise dread spread through a household?
Money stress is contagious inside a home in a way that other stresses are not, because the budget is shared and the silence about it is shared too. One partner stops mentioning a purchase. The other stops asking about the bank balance. Both interpret the quiet as worry, and both worry more because of the quiet. Psychologists call this emotional contagion: moods pass between people who live together, often without a word being said.
Children pick it up as well, even when parents believe they are shielding them. They notice the canceled plans, the shorter answers, the tension at the table. They rarely know the cause, so they invent one, and invented causes are usually scarier than the truth. A short, honest sentence — money is tighter this year, the house is fine, here is what we are doing — protects a child far better than a brave silence.
The antidote inside a household is a meeting, not a mood. Fifteen minutes with the actual numbers, a written plan for either outcome of today’s decision, and an agreement about what gets cut first and what is protected no matter what. Plans do not make a rate rise painless. They make it bounded, and bounded problems are problems the mind can set down.
What can mortgage holders actually control today?
Less than they want, more than they feel. Nobody in a household controls the RBA board, the September CPI print, or the bank’s next move. But households do control the next three decisions: whether to check the announcement once or refresh it all afternoon, whether to call the lender this week or wait for the letter, and whether to talk about the budget tonight or let it sit unspoken for another month.
Practical steps, in order of impact: first, work out the real figure for your own loan at 4.85%, not the average quoted in the news. Second, call your lender before the new repayment lands and ask about offset, redraw and hardship options — lenders have whole teams for this, and asking early is treated very differently from asking late. Third, protect one non-negotiable in the budget, even a small one, so the household does not feel like it is losing everything at once. Psychologists call this preserving a sense of agency: one choice you made, on purpose, in a week when most choices felt imposed.
If the RBA surprises and holds today, the lesson is the same. A hold is breathing room, not a reprieve, and the households that use it to build a buffer — even a small one — will face the next decision with steadier nerves than those who spend it immediately.
Frequently asked questions
What is the RBA expected to decide on 3 November 2026? All four major banks expect a 25 basis point rise, taking the cash rate from 4.60% to 4.85%, the fifth increase of 2026. The decision is due at 2:30 p.m. Sydney time.
Why is the RBA raising rates again? Headline inflation reached 4.3% in the year to September 2026, with underlying inflation around 3.6 to 3.7%, above the bank’s 2 to 3% target band, prompting further tightening despite slowing growth.
Why does waiting for a rate decision cause so much anxiety? Because households rehearse the worst outcome in advance, a pattern called anticipatory anxiety, and because losses feel larger than equivalent gains, so a higher repayment weighs more heavily than the same amount gained elsewhere.
What should mortgage holders do after a rate rise? Work out your own new repayment figure, contact your lender early about offset or hardship options, and agree a household plan that protects at least one non-negotiable expense.
Is rate-rise stress a normal reaction? Yes. Money stress tied to housing is one of the most common forms of financial anxiety, and it rises sharply around decision days when uncertainty is highest.
Key Takeaways
- The RBA is widely expected to lift the cash rate to 4.85% on 3 November 2026, the fifth rise this year.
- Most of the pain arrives before the announcement, as households rehearse a future that has not happened yet.
- Loss aversion makes a higher repayment feel larger than the same amount gained elsewhere.
- A written plan for either outcome, plus one protected expense, restores a sense of control.
Try it on our site
If money worry is sitting heavily today, try Name Your Feeling to pin the feeling down, a Thought Reframe for the worst-case budget story, or a calming Relaxation Technique. Find them all at the Wellness Tools hub.
Related reading: New Zealand Cost-of-Living Anxiety: Why the Weekly Shop Feels Like a Verdict, US Election Eve Anxiety, and GTA 6 Hype and the Psychology of Waiting.
This article is for education only and is not financial or medical advice. If you are struggling, consider speaking to a licensed professional. In Australia, Lifeline is available on 13 11 14, and the National Debt Helpline on 1800 007 007.